

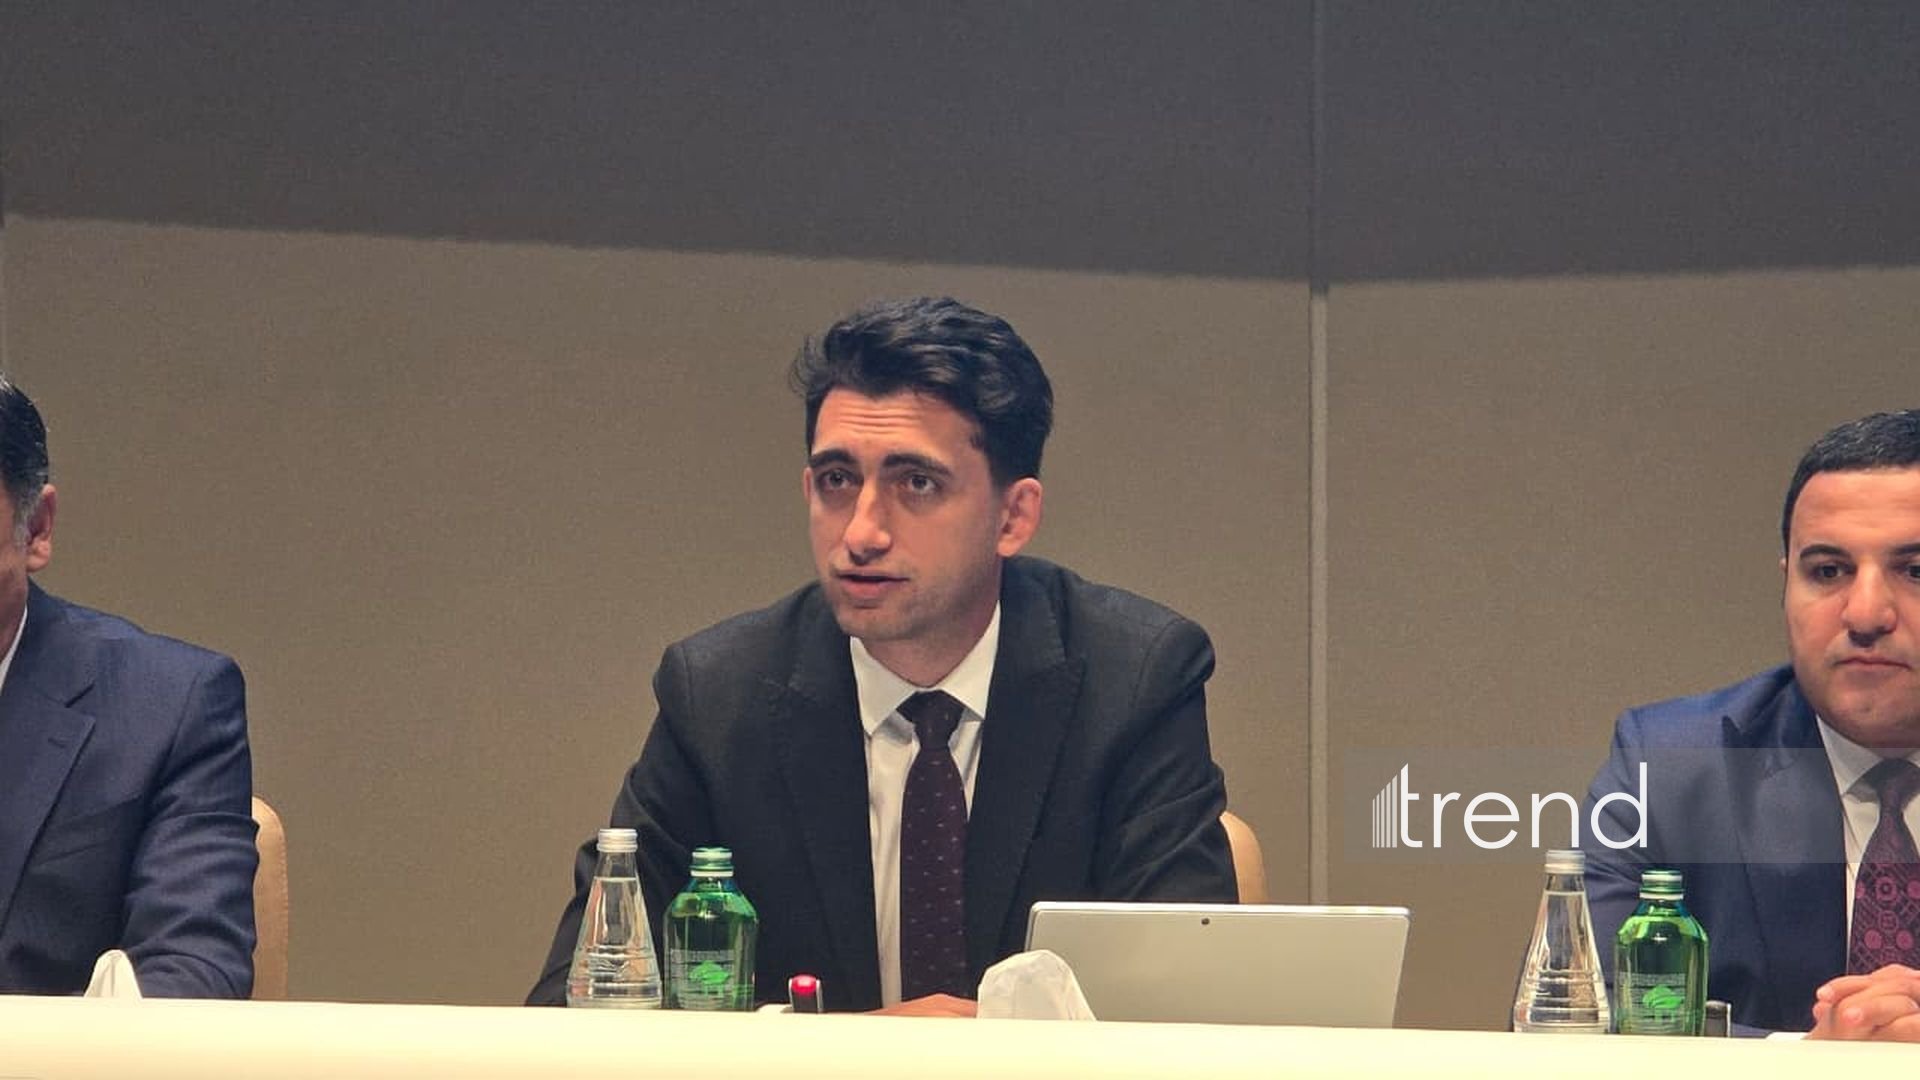
BAKU, Azerbaijan, October 15. The key aim of the regulatory measures introduced by the Central Bank of Azerbaijan (CBA) for consumer loans is to prevent excessive indebtedness and ensure that borrowers take on loans commensurate with their income, CBA Executive Director Shahin Mahmudzade said at a news conference in Baku on Thursday dedicated to the presentation of the Financial Stability Report, Trend's correspondent reports from the event.
He noted that the consumer lending requirements are designed to protect citizens' financial interests and prevent them from taking out loans without adequately assessing their ability to repay them.
"Our goal is to ensure that people do not borrow more than they need. The requirements we have implemented, such as restricting lending when the debt-to-income ratio exceeds 70%, limiting the issuance of consumer loans in foreign currency, imposing additional capital requirements for credit cards, and other measures, all serve this same purpose. People shouldn’t take out loans they don’t need. Furthermore, when a loan is taken, the amount should be commensurate with the borrower's income," he mentioned.
According to the CBA executive, the new regulatory measures, including a mechanism that allows individuals to restrict their own ability to take out loans, as well as new rules governing online lending, are also aimed at reducing financial risks for citizens.
Mahmudzade pointed out that the tightening of requirements for bank lending could create a risk that some individuals seeking to borrow might turn to alternative sources of financing, such as pawnshops or informal credit channels.
"If a person is unable to obtain a loan from a bank, he/she may turn to other sources of financing, including pawnshops. Subsequently, there is a possibility that he/she might resort to informal channels. This could be a consequence of tightening requirements within the banking sector. Therefore, it is essential to assess the overall impact of regulatory measures," he explained.
He added that when drafting regulations for the consumer credit market, the CBA considers not only the situation within the banking sector but also the potential impact these requirements may have on the borrowing behavior of citizens.
According to the executive, the objective of the regulation is not to make consumer credit entirely inaccessible, but rather to protect citizens from making ill-considered financial decisions. At the same time, fostering a culture of responsible borrowing within society is of great importance.
"We are implementing these rules to encourage people to refrain from non-essential expenditures and to avoid increasing their consumption through additional debt. Some expenses generate no added value, yet they increase an individual's debt burden. Our goal is for people to understand the essence of these changes and to realize that excessive borrowing primarily harms them," emphasized Mahmudzade.
He noted that while regulatory measures help mitigate financial risks for citizens, the development of responsible financial behavior also requires individuals to properly assess their own expenses and borrowing needs. "We can protect people to a certain extent through our own regulations. However, individuals must also safeguard their own financial standing by avoiding unnecessary expenses and additional indebtedness," added the CBA executive.
Touching upon statistics regarding informal borrowing, Mahmudzade noted that it’s difficult to assert definitively whether there has been a growth in this area due to the absence of official statistics or relevant reporting for such transactions. Therefore, it’s impossible to confirm whether the volume of informal lending is rising or falling.


