

BAKU, Azerbaijan, October 14. Global demand for natural gas will continue to grow at least through 2035, increasing by nearly 20% compared to 2025 and reaching 5.180 trillion cubic meters.
According to GlobalData’s latest report, “GlobalData Gas Market Outlook 2026,” the expected surplus of liquefied natural gas (LNG) on the global market will materialize later than previously anticipated and will be short-lived.
The forecast indicates that global demand for gas will grow by an average of 1.8% per year, from 2025 through 2035.
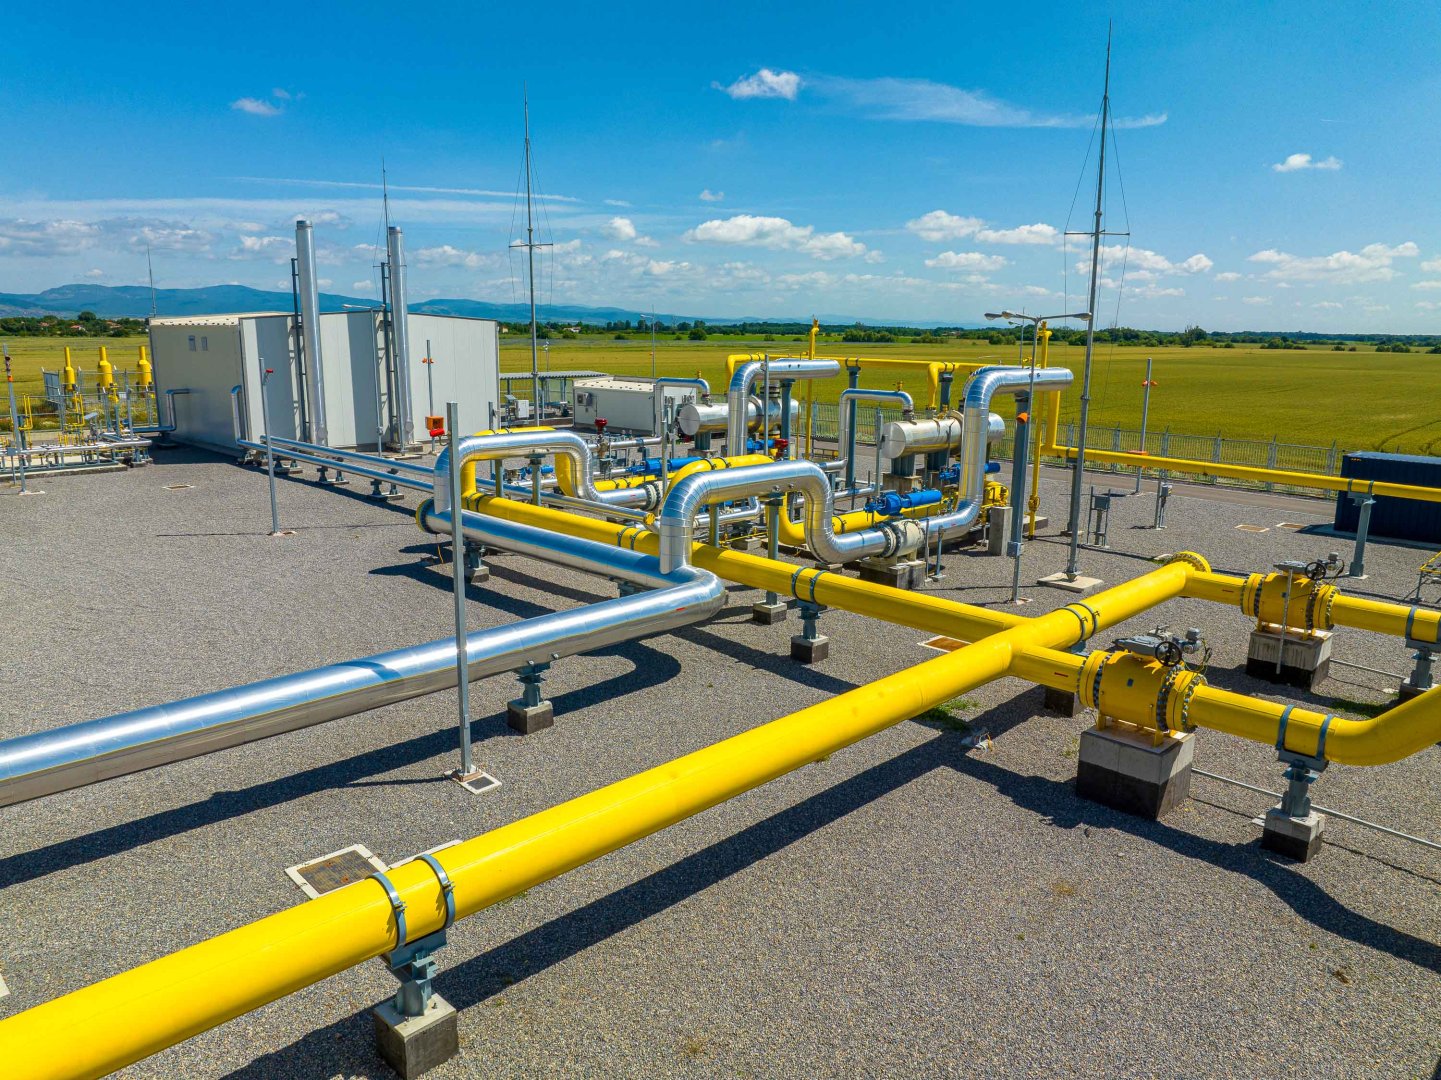
GlobalData notes that the key constraint on increasing gas supply over the next decade will not be the volume of raw material reserves, but rather the development of export infrastructure, including pipelines and natural gas liquefaction plants.
“The market has been discussing a gas surplus for two years. GlobalData’s data on individual fields shows that a surplus does indeed exist, but it will be short-lived. The main question for the 2030s is not whether there is enough gas in the ground, but whether pipelines and LNG plants will be built in the right places,” said Paul Hasselbrinck, GlobalData’s lead analyst for the oil and gas sector.
According to GlobalData’s estimates, natural gas production in the Middle East will decline by 98 billion cubic meters this year. The report notes that, as a result, global gas supply will increase by only 14.9 billion cubic meters, while demand is expected to grow by 37.7 billion cubic meters. The company estimates that, due to supply constraints, it will not be possible to meet demand ranging from 38 to 59 billion cubic meters.
Hasselbrinck noted that the events of 2026 were the result of transit disruptions, not a shortage of resources. According to him, prices in the European and Asian markets are reacting to supply disruptions, the closure of one of the main maritime routes, and damage to part of the gas liquefaction capacity: “At the same time, global gas production continued to grow in 2026.”
According to GlobalData’s forecast, as exports from the Gulf countries recover, the market will gradually return to normal. However, the recovery will take longer than expected.
Gas exports from the Gulf countries are expected to begin recovering starting in 2027: “By 2031, liquefied natural gas (LNG) facilities with a total capacity of 281.3 million metric tons per year, which are currently under construction or being commissioned, are also expected to come online. The majority of these facilities are located in the U.S. and Qatar.”
"The gas supply surplus will peak at approximately 200 billion cubic meters in 2029. However, the gap will then narrow rapidly: the market will reach equilibrium in 2034, and a shortage will emerge in 2035.
For 166 billion cubic meters of gas scheduled for production in 2035, export routes backed by final investment decisions or the necessary permits have not yet been approved. The bulk of these volumes comes from Senegal, Tanzania, Mauritania, Guyana, and Cyprus,” the company reports.
According to Hasselbrinck’s assessment, the U.S. faces the opposite problem: to meet the needs of approved gas liquefaction projects for which final investment decisions have been made, approximately 400 billion cubic meters more gas will be required in 2035 than U.S. companies have so far committed to producing.
GlobalData believes that the future dynamics of the global gas market will depend on the development of export infrastructure in new production regions, as well as on whether U.S. gas production can grow at the rates necessary to meet liquefaction capacity requirements.
The company also notes that the risks to the baseline forecast for gas demand are primarily related to the possibility of a decline: "Potential growth in demand driven by cheaper LNG and increased electricity consumption associated with the development of artificial intelligence could collectively account for up to 3.5% of projected demand in 2035. This is roughly one-quarter of the potential 8% decline in demand should the energy transition accelerate.”


