

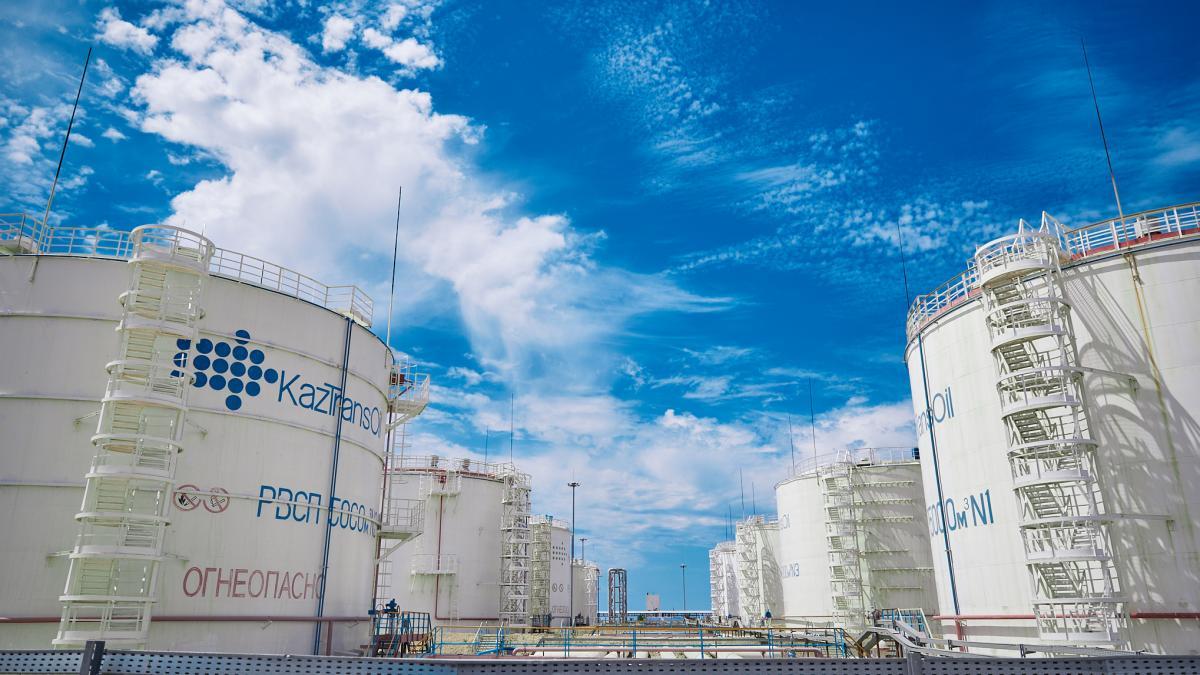
BAKU, Azerbaijan, October 6. On October 5, S&P Global Ratings upgraded KazTransOil's (KTO) long-term issuer credit rating to 'BBB' from 'BBB-' following an upgrade of Kazakhstan's sovereign rating and a revision of the country's risk assessment, the agency said.
The outlook on KTO remains stable, in line with the outlook on its parent company, KazMunayGas NC JSC (KMG).
S&P said the upgrade reflects easing sovereign constraints and a more favorable economic environment, which support a higher assessment of KTO's business risk profile.
"The upgrade follows that of Kazakhstan and a revision of our country risk assessment. In our view, the easing of sovereign constraints and a more benign economic environment support a higher positioning of KTO's business risk profile within our fair category," S&P said.
The agency expects KTO to generate solid cash flow and maintain minimal leverage in 2026-2028, supported by recurring EBITDA and limited capital spending.
S&P forecasts KTO's adjusted EBITDA at 116 billion tenge ($255 million) in 2026, down from 149 billion tenge ($327.5 million) in 2025, before rising to 140 billion-150 billion tenge ($307.7 million-$329.7 million) in 2027-2028. The decline in 2026 is due to the absence of unusually high export revenue recorded in 2025 amid attacks on KTO's key competitor, the Caspian Pipeline Consortium (CPC).
"From 2027, domestic tariff hikes should offset cost inflation and a 2%-3% annual transportation volume decrease, due to a structural decline in extraction at domestic oilfields," the agency said.
S&P expects KTO's capital expenditure to remain limited to maintenance and minor growth projects, including the TON-2 pipeline expansion, and to be fully funded by existing cash. The agency assumes no new debt under its base case.
"Combined with minimal interest and working capital needs, this should enable healthy free operating cash flow," S&P said, adding that KTO's dividend payouts could be reduced if investment needs increase.
S&P also said its assessment of KTO is supported by the company's role as a strategic infrastructure services provider in Kazakhstan. KTO is one of the country's two oil pipeline operators, along with CPC, and transports up to half of Kazakhstan's crude oil while covering virtually all crude oil requirements of domestic refineries.
The agency noted that KTO benefits from route diversification, with domestic shipments accounting for about 40% of oil accepted in 2025, alongside higher-margin transit and export destinations.
The stable outlook reflects S&P's expectation that KTO will maintain debt to EBITDA below 1.0x and funds from operations (FFO) to debt above 60%. The agency assumes no new debt issuance under its base case and expects the company's financial policy to remain conservative.
The exchange rate used by Trend is $1 = 454.98 tenge.


